October is when the year becomes real.
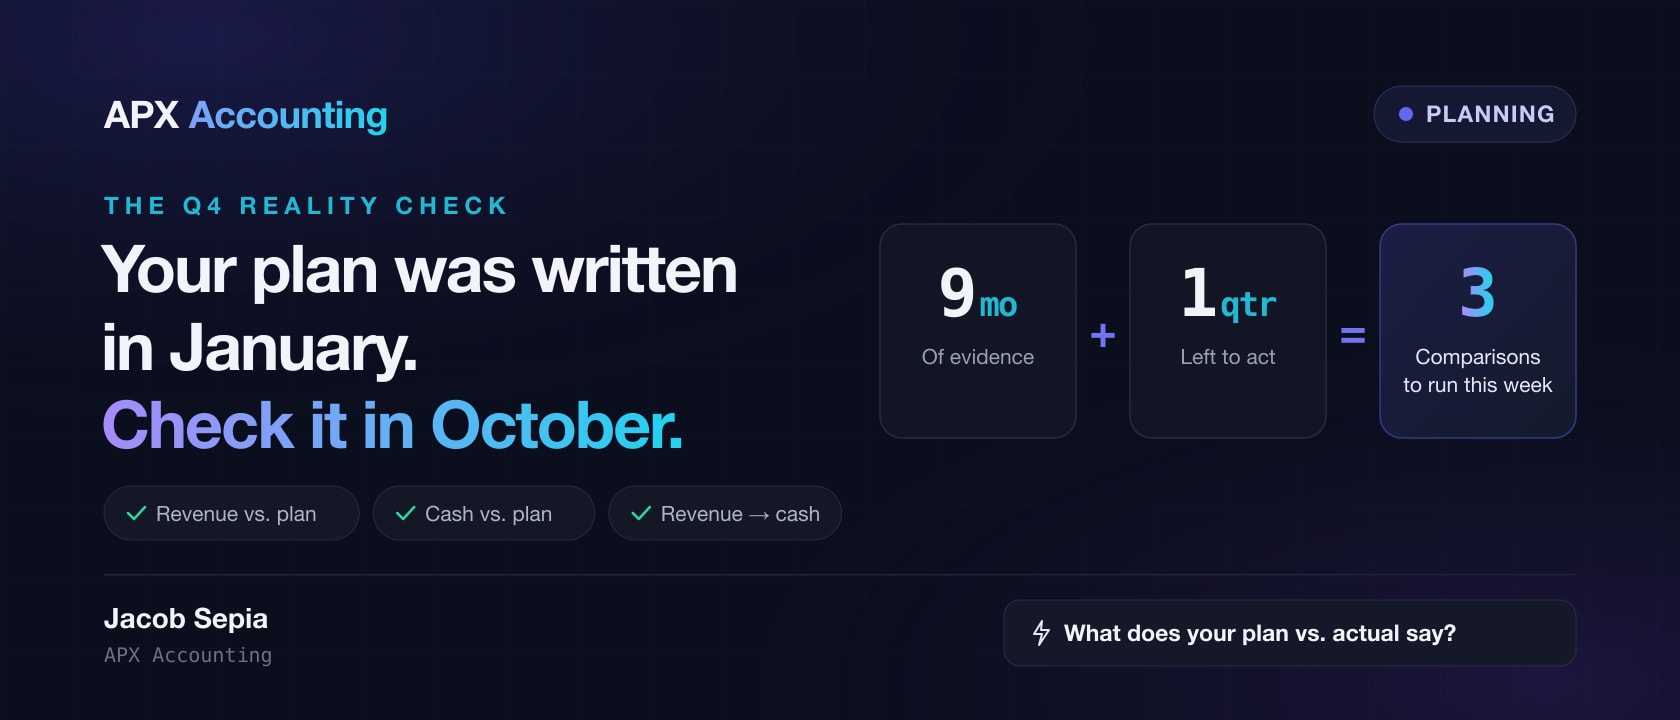
Your plan for the year was written in January, when everything was possible and nothing was late. Nine months later, it needs a reality check. Not because planning is useless, but because you now have nine months of evidence and one quarter left to act on it.
Most founders I meet haven't put the plan and the actuals side by side, in one sitting, since the plan was approved. That's nine months of decisions made on the plan's memory instead of the year's reality.
Q4 is your chance to fix that. Here's how to run the check, how to read what it tells you, and what to do with the time that's left.
Three Comparisons to Run This Week
You don't need a full reforecast to start. You need three comparisons, month by month, January to now.
1. Planned vs. actual revenue
Line up the revenue you planned for each month against what you actually booked. Don't just look at the year-to-date total. Totals hide patterns. A business that's 5% behind for the year might be 20% behind for the last three months and coasting on a strong first quarter. That's a very different conversation.
2. Planned vs. actual cash balance
Revenue tells you about sales. Cash tells you about survival. Compare the cash balance you expected at the end of each month with the one you actually had. If cash has drifted further from the plan than revenue has, something between the sale and the bank account is leaking.
3. Is revenue actually turning into cash?
This third comparison often tells the real story. Sales can look healthy while overdue invoices pile up, inventory builds, or deposits get spent on costs that came early. Look at how your receivables have grown compared to revenue. If revenue is up 10% and receivables are up 40%, you're not growing, you're lending.
How to Read the Gaps
Every gap between plan and actual falls into one of a few categories, and each one calls for a different response.
- Timing or permanent? A deal that slipped from September to November is timing. A customer you lost is permanent. Timing gaps need patience and cash planning. Permanent gaps need the plan to change.
- Price or volume? Are you selling less, or selling the same amount for less? Discounting shows up as a revenue miss that looks like a sales problem but is really a pricing problem.
- Mix? Revenue can hit the plan while margin misses it, because the business sold more of the low-margin work and less of the high-margin work. Check gross margin by product, service line, or customer type, not just in total.
- Cost drift. Compare spending by category too. Software, contractors, and travel are where costs quietly outrun the plan, usually without anyone deciding they should.
The goal isn't to assign blame for the gap. It's to understand which assumptions in the plan turned out to be wrong, because those same assumptions are probably about to go into next year's plan.
What to Do With the Quarter That's Left
Once you know where you stand, Q4 gives you real levers. Here are the ones I'd look at first.
Adjust spending to the year you're actually having
If revenue is behind and the gap is permanent, spending should come down to match, starting with the costs nobody would notice. If you're ahead, decide deliberately where the extra goes instead of letting it get absorbed.
Run a collections push
Every dollar sitting in receivables at year-end is a dollar you earned but can't use. Work the aging report invoice by invoice in November. Many customers also have year-end budget to spend, and a well-timed follow-up can land payments that would otherwise slide into January.
Time your big decisions
Hiring, equipment purchases, and other large commitments all have a cash impact, and their timing relative to your year-end can matter. Model the impact before you commit, not after.
Talk to your CPA firm in November, not March
Several year-end decisions have a hard deadline of December 31 and can't be fixed after the fact. The best time to review them with your CPA firm is while there's still time to act. We prepare the numbers and the year-end file. Having current books in November is what makes that conversation useful instead of hypothetical.
Review your pricing for next year
If margin missed the plan, Q4 is when to fix pricing, so new rates are in place on January 1 instead of being debated in April.
Build Next Year's Plan From the Evidence
The most valuable thing you get from a Q4 reality check is a better plan for next year. Three changes make the biggest difference.
- Start from actuals. Build next year from this year's real run-rate, real margins, and real collection times, not from last January's assumptions with ten percent added on top.
- Plan on drivers, not totals. Instead of "revenue: $3.2M," plan the drivers underneath it: customers, average deal size, close rates, churn, utilization. When reality moves, you can see exactly which driver moved.
- Replace the static budget with a rolling forecast. A plan written once a year is out of date by March. A rolling forecast, updated monthly with actuals, is never more than a few weeks old.
Where Technology Helps
The reason most companies don't do this mid-year is that it's painful. Pulling actuals, lining them up against a plan built in a different spreadsheet, and rebuilding the forecast by hand takes days.
It doesn't have to. When the books are current and connected, plan-vs-actual is a report, not a project. Every APX client has a live portal, built in-house, that shows budget against actuals and a rolling 13-week and 26-week cash flow forecast at any time. Its scenario builder lets you test a decision before you make it: switch on a new hire, raise prices, take on a loan, or lose a major customer, and see what happens to cash over the next quarter.
That's the whole idea behind combining accounting with technology. The software keeps the numbers current. The accountant helps you decide what to do about them.
The One-Hour Agenda
If you do nothing else this month, book one hour with your leadership team and your finance lead, and walk through this:
- Planned vs. actual revenue, by month.
- Planned vs. actual cash, by month.
- Revenue vs. receivables growth: is revenue turning into cash?
- The three biggest gaps, and whether each is timing or permanent.
- Three actions for Q4, each with an owner and a date.
The Bottom Line
The question that changes the conversation is simple: what does your plan-vs-actual look like right now?
If you don't know, that's the first thing to fix. There's still a full quarter left, which is enough time to adjust spending, accelerate collections, and build next year's plan around what the numbers are actually telling you.
Our Fractional CFO service runs this review with clients every quarter. If you'd like a second set of eyes on your year, book a call and bring your plan. We'll bring the questions.